

Ualett analysis by Appwee
When I first tried Ualett, I understood its appeal almost immediately: it is a finance app aimed at people whose income comes from gigs, short contracts, or several small jobs rather than one predictable paycheck. That focus makes it more interesting than a general budgeting tool, especially if your money arrives in uneven bursts and you need a clearer way to think about work-related cash flow.
I also found it useful to consider Ualett in a household setting. A partner, parent, or housemate may help with bills, transport, or daily planning, but that does not mean everyone should use the same account or see the same financial information. The app can be part of a shared routine without turning into a shared wallet. That distinction matters more than it first appears.
Ualett is free, has an Everyone content rating, and is developed by Cabicash Solutions, Inc. It has been available since August 21, 2018, and its current version is 2.73.0 for devices running Android 8.0 or later. With over 500 thousand installs and an average rating of 4.6 from around 7.6 thousand ratings, it has clearly attracted a sizeable audience without pretending to be a universal banking replacement.
How Ualett fits into a shared household routine
A practical scenario for gig income
Imagine one person in a household driving, delivering, freelancing, or accepting short assignments. Their income may look healthy over a full month but still feel tight on a particular Tuesday because fuel, meals, phone costs, and a bill arrive before the next payment. A conventional banking app can show the balance, but it does not necessarily help that person think through the irregular rhythm of gig work.
This is where I see Ualett making the most sense. I would use it as a personal financial workspace for the worker, then bring only the useful conclusions into a household conversation. For example, instead of handing over account access, the worker could say, “This week’s work money needs to cover fuel first, so we should delay the optional purchase.” The app becomes a planning aid rather than a reason for everyone to share sensitive credentials.
That approach is especially helpful when a household has mixed income. One person may be paid on a fixed schedule while another receives money through gigs. Treating both streams as if they behave identically can create bad decisions. Ualett’s worker-oriented purpose encourages the gig worker to assess money in the context of earning activity, not just as a static bank balance.
I would not expect it to replace a complete household budget by itself. A family still needs a shared view of rent, utilities, groceries, debt payments, and savings goals. Ualett is better positioned on the worker side of that conversation. Its value is strongest when it helps one person understand their own variable income before the household makes a commitment based on it.
Why separate accounts matter
On a shared phone, the temptation is to let several people use one logged-in finance app. I think that is a poor habit, even when everyone trusts one another. A finance account can contain information that is personal, and accidental changes or misunderstandings become more likely when the boundaries are unclear.
My recommendation is simple: the person earning through gigs should maintain their own Ualett account and device access, while the household coordinates through agreed summaries. If another adult needs to help with planning, that person can participate in a conversation without automatically becoming the account holder. This keeps responsibility visible: the worker knows what was entered, and the household knows which figures are being discussed.
This matters even more on a family tablet or a phone that children sometimes borrow. An Everyone rating describes the general suitability of the app’s content, not a promise that a child should manage adult finances. I would keep financial access with the responsible adult and avoid leaving an unlocked account available on a common device.
Setting expectations before the first use
Ualett is easier to use well when the household agrees on its role before anyone starts relying on it. Is it for the worker’s personal planning? Is it being used to prepare a weekly amount for shared expenses? Is another person simply helping interpret the numbers? Those are different arrangements, and confusion usually comes from treating them as one.
I would begin with a short agreement: the account belongs to the gig worker, household expenses are discussed separately, and no one assumes that money shown in the app is automatically available for every purpose. This sounds obvious, but irregular earnings often create false confidence. A strong week can make a household spend as though that level will continue, even when the next week may be quieter.
Another useful boundary is deciding when to review the information. A daily check can become stressful and may encourage impulsive choices. A weekly review is often more practical: look at recent work, immediate costs, upcoming household obligations, and the amount that should remain untouched. I would use Ualett as a prompt for that conversation, not as an excuse to monitor another person constantly.
Coordination without handing over control
The best shared-use workflow I found is based on categories of responsibility. The worker tracks their gig-related situation in Ualett. The household keeps its own list of fixed commitments. Once or twice during the week, the two views are compared. This avoids forcing a finance app designed around gig workers to become a full family accounting system.
For instance, a courier might need to reserve money for fuel and maintenance before deciding how much can go toward groceries. A partner may handle the grocery list but not know how much the week’s work actually cost to produce. A short check-in connects those facts. The important insight is that gross earnings and usable household money are not the same thing, and the app can support a more careful discussion of that difference.
I also like the idea of using a neutral routine rather than discussing money only when there is a problem. A household could review the worker’s position before a large purchase, before a bill deadline, or when planning a day off. The point is not to demand constant reporting. It is to create a predictable moment when both people can make decisions with the same understanding.
For shared devices, I would be more cautious. If Ualett is installed on a phone used by several people, the account holder should sign out or use the device’s normal privacy protections when appropriate. I would not rely on the app as a substitute for device-level separation. The practical rule is that shared hardware does not require shared financial identity.
What the app does well for gig workers
Ualett’s clearest strength is its narrow audience. Many finance apps begin with the assumption that users have a regular salary, predictable paydays, and familiar monthly categories. Gig workers often need a different mental model. Their challenge is not simply recording spending; it is deciding what income is truly usable after the costs and uncertainty attached to earning it.
That focus makes Ualett more approachable for someone who feels that a traditional budgeting app asks too many questions before becoming useful. I can see a new delivery worker or freelancer opening it with a specific concern: “How should I handle money from this kind of work?” The app’s identity gives that person a clearer starting point than a generic expense tracker.
It is also a reasonable choice for someone who wants a dedicated space for work-related financial thinking rather than mixing every household transaction together. Separating those concerns can reveal patterns that disappear inside one large bank statement. If the worker later discusses a contribution to rent or groceries, they can do so with a better understanding of what their work actually supports.
The app’s free price lowers the barrier to trying that approach. I would still judge it by whether it changes behavior, not simply by whether it costs money. A free finance app that is ignored is less valuable than a paid tool that genuinely fits someone’s routine, but Ualett has a fair chance with users who need a focused entry point and do not want to commit immediately.
Where I would be careful
The same specialization that makes Ualett appealing can make it less suitable for other users. If your main goal is detailed household budgeting, investment tracking, bill automation, or a complete view of several bank accounts, I would compare it with a broader personal finance service. A gig-worker focus does not automatically make an app the best tool for every financial task.
I would also avoid treating Ualett as a guarantee that irregular income becomes predictable. No app can remove slow work periods, changing expenses, or the difference between a busy week and a profitable week. The user still needs judgment. If the app encourages you to spend every strong week’s earnings, it is being used incorrectly, regardless of how convenient the interface feels.
Another limitation is social rather than technical: shared finances can become uncomfortable when one person expects complete visibility into another person’s account. Ualett cannot solve a disagreement about trust or responsibility. Before introducing it into a couple’s routine, I would agree on what information is shared and what remains personal. That conversation is more important than any particular screen inside the app.
Families should also be realistic about age. The Everyone label makes the app broadly suitable from a content perspective, but an adult should remain responsible for financial decisions and account security. A teenager might help with a household planning exercise, yet I would not give a child unrestricted access simply because the app is not marked for mature audiences. Content suitability and financial readiness are separate questions.
Small habits that make the experience more useful
My first practical tip is to review money after considering the cost of earning it. A gig payment can look attractive until fuel, equipment, mobile data, travel, or other work necessities are considered. I would use Ualett alongside a simple note about those costs, then make household plans from the remainder rather than the headline payment.
My second tip is to separate “available now” from “safe to spend.” Those phrases are not interchangeable. Money sitting in an account may be needed for transportation to the next job, a recurring bill, or a quiet period. When coordinating with a partner, I would communicate the safe-to-spend amount and explain the main reservation behind it. That makes the conversation more useful than sharing a raw balance.
My third tip is to establish a pause before transferring irregular income into household spending. A worker can review recent earnings, immediate work costs, and near-term commitments before deciding what to contribute. This creates a buffer against the emotional effect of a particularly good day. It also makes contributions more consistent when income changes from week to week.
A fourth useful habit is to keep personal and shared goals distinct. Ualett can help the worker think about their work income, while a household note or conversation can cover joint priorities. Combining everything too early makes it difficult to tell whether a shortfall came from low earnings, high work costs, or ordinary household spending. Keeping the stages separate improves the quality of the decision.
How it compares with familiar alternatives
Compared with a standard banking app, Ualett offers a more worker-centered perspective. A bank app is usually the final record of money movement, but it may not help a gig worker interpret income that arrives irregularly. I would keep the banking app for checking transactions and account security, then use Ualett when the question is how gig earnings fit into a broader plan.
Compared with a spreadsheet, Ualett is likely to feel less demanding for someone who does not want to build formulas, categories, and weekly templates. A spreadsheet can be more flexible and easier to share with a partner, but it requires discipline and setup. Ualett’s advantage is having a defined purpose; its trade-off is that it may not adapt as freely to an unusual household system.
Compared with a general budgeting app, the choice depends on the user’s priority. A broad budgeting tool may be better for envelopes, subscriptions, savings targets, and multiple household accounts. Ualett makes more sense when the central problem is the uneven nature of gig work. I would choose the specialized app first for the worker’s side of the picture, then add another method only if the household needs more detail.
Compared with simply talking through finances, Ualett adds structure, but it should not replace communication. Numbers can help a couple avoid vague assumptions, yet they cannot decide what feels fair or which expense matters most. The strongest setup combines the app’s focused planning with a calm, agreed conversation about shared obligations.
Who should use it and who should skip it
I would recommend Ualett to a gig worker who wants a dedicated finance tool, especially someone whose income changes frequently and who needs to distinguish work money from household spending. It is also worth considering for a couple where one person earns through gigs and both want a clearer weekly planning routine without sharing every account detail.
I would be less enthusiastic for someone with a regular salary who mainly wants investment research, detailed family accounting, or a complete banking dashboard. That person may find a broader finance app more efficient. I would also suggest skipping it if you are unwilling to review your numbers consistently; the app cannot create a habit that the user does not maintain.
For a household with children, I would use it as an adult-managed tool. A child can learn from a discussion about budgeting, but the account should remain within the adult’s financial boundaries. On a shared device, I would be especially careful about account access and would never confuse an Everyone content rating with permission for unsupervised financial use.
My household verdict
After using Ualett with the shared-use question in mind, I see it as a focused companion for the person doing gig work, not a universal family money center. Its strongest contribution is helping irregular earners think before they commit money to household spending. That is a real need, and many ordinary banking screens do not address it directly.
I appreciate that the app is free and accessible on older Android devices, while its established presence and strong average rating suggest that many users find the approach worthwhile. Still, I would keep expectations grounded. Ualett does not remove uncertainty, settle household disagreements, or replace a complete budget when a family needs one.
My final recommendation is to give it a trial if gig income is the financial problem you are trying to solve. Keep the account boundaries clear, agree on what gets shared, and review work costs before treating earnings as household money. Used that way, Ualett can turn an unpredictable income stream into a more manageable conversation. If your needs extend far beyond gig-worker planning, pair it with a broader tool or choose a different finance app altogether.
Gallery
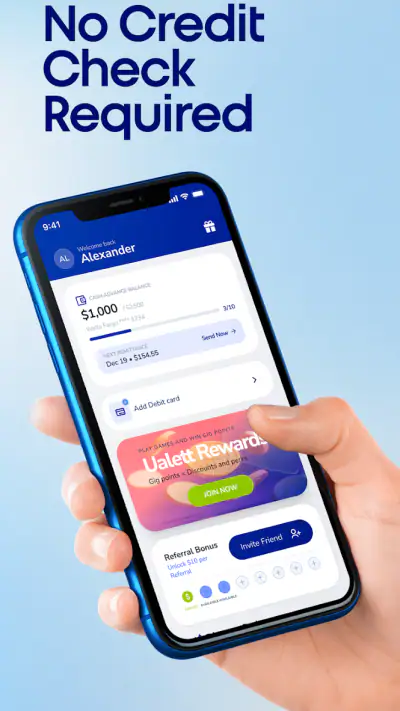
Ualett Pros and Cons
- Fast access to earned wages through a simple mobile application.
- Useful for managing cash flow between regular paydays.
- Application is designed with a straightforward
- easy-to-use interface.
- Can help cover urgent expenses without relying on traditional overdrafts.
- Digital process reduces the need for paperwork or branch visits.
- Availability may depend on employer participation and eligibility requirements.
- Fees or transfer costs can reduce the amount you receive.
- Advance limits may be too low for larger unexpected expenses.
- Not available in every country or for all types of workers.
- Frequent advances could make budgeting and payday planning more difficult.
Ualett Frequently Asked Questions
What is Ualett and what can I use it for?
Ualett is a financial app designed to help users manage everyday money-related tasks from a mobile device. Depending on your location and eligibility, it may provide access to services such as account management, payments, transfers, or other digital financial tools. Available features can vary by country, so review the information shown during registration before relying on the app for essential transactions.
How do I create an account on Ualett?
To start using Ualett, download the official app and follow the registration process. You will generally need to provide personal information, a valid phone number or email address, and possibly identity documentation. Make sure every detail matches your official records, because incorrect information can delay verification. You should also read the privacy policy and terms before completing the sign-up process.
Is Ualett safe to use for managing money?
Ualett should be downloaded only from an official app store or an authorized source, and users should keep the application updated. As with any financial service, protect your password, verification codes, and device access, and never share sensitive information through unofficial messages. Security features and verification requirements may differ by region, so check the app’s current policies and contact support if you notice suspicious activity.
Are there fees or limits when using Ualett?
Ualett may apply fees, transaction limits, withdrawal restrictions, or other conditions depending on the service you use and your country. Some charges may be displayed before confirming a transaction, while others can be explained in the pricing or terms section. Before adding funds or sending money, carefully review the total cost, processing time, and daily or monthly limits applicable to your account.
What should I do if I cannot log in or complete a transaction?
If Ualett is not working correctly, first check your internet connection, update the app, and confirm that you are using the correct login details. Avoid repeatedly entering incorrect verification information, as this may temporarily lock your account. For payment delays, failed transfers, or identity-verification problems, use the official in-app help or support channels and keep any relevant transaction reference numbers.














